
You can remove a hard inquiry only if it's inaccurate, unauthorized, or fraudulent. If you applied for the credit yourself, that inquiry is accurate and generally has to run its course. The good news is that inquiries stay on your report for up to 24 months but FICO typically only counts the past 12, and disputing a wrong one costs nothing. You can file directly with the credit bureaus, use official channels like the Consumer Financial Protection Bureau and Identitytheft, or work with a firm like Pioneercreditsolution if you want someone else to manage the paperwork.
TL;DR:
- Only inaccurate, fraudulent, or unauthorized inquiries can be removed; legitimate applications generally must remain on your report for up to 24 months.
- Hard inquiries typically impact your score for about 12 months, with their effect diminishing over time, especially if you rate shop within a short window.
- Deleting authorized inquiries is usually impossible, but fraud-related, duplicated, or incorrectly coded inquiries are strong candidates for removal.
- Filing disputes involves gathering evidence, contacting creditors, and challenging the bureaus within 30 days, with faster results possible through direct creditor contact for clerical errors.
- Most credit scores gain only two to five points from removing a single inquiry, and inquiries are a minor factor compared to payment history and utilization.
Table of Contents
- What Is a Hard Inquiry, and How Is It Different From a Soft One?
- How Long Do Hard Inquiries Stay on Your Credit Report?
- Which Hard Inquiries Can You Actually Remove?
- How to Dispute a Hard Inquiry Step by Step
- When Calling the Creditor First Works Faster Than a Bureau Dispute
- What to Do If the Inquiry Is Tied to Identity Theft
- What Happens After You File a Dispute?
- When to Handle This Yourself vs. When to Get Help
- How Pioneercreditsolution Handles Inquiry Disputes and Credit Cleanup
- Sources
- FAQ
What Is a Hard Inquiry, and How Is It Different From a Soft One?
A hard inquiry happens when a lender pulls your full credit file because you applied for new credit. It shows up when you apply for a credit card, an auto loan, a personal loan, or a mortgage, and it can shave a few points off your score.
A soft inquiry is different. It happens when you check your own credit, when a lender pre-qualifies you for an offer, or when an existing creditor reviews your account. Soft pulls never affect your score, no matter how often they happen.
One thing trips up a lot of consumers: the name on the inquiry might not match the brand you applied through.
- A car dealer's financing application might show up under the actual bank or credit union that underwrote the loan.
- A retail credit card might list the bank that issues it, not the store.
- A mortgage inquiry might show a wholesale lender you never spoke with directly.
Before you assume an inquiry is fraudulent, check whether it lines up with something you actually applied for, even if the name looks unfamiliar at first glance.
How Long Do Hard Inquiries Stay on Your Credit Report?
Hard inquiries sit on your credit report for up to 24 months, but they don't hurt your score for that entire stretch. FICO's scoring model generally only factors in inquiries from the past 12 months, and VantageScore treats them similarly, with the impact fading well before the two-year mark. Most inquiries cost you fewer than five points, and that effect shrinks the longer the account sits on file.
Quick fact: if you're rate shopping for a mortgage, auto loan, or student loan, FICO groups multiple inquiries of the same type into a single event as long as they fall within a defined rate-shopping window, commonly around 45 days depending on the scoring model. That means comparing offers from five lenders in two weeks usually counts as one inquiry, not five.
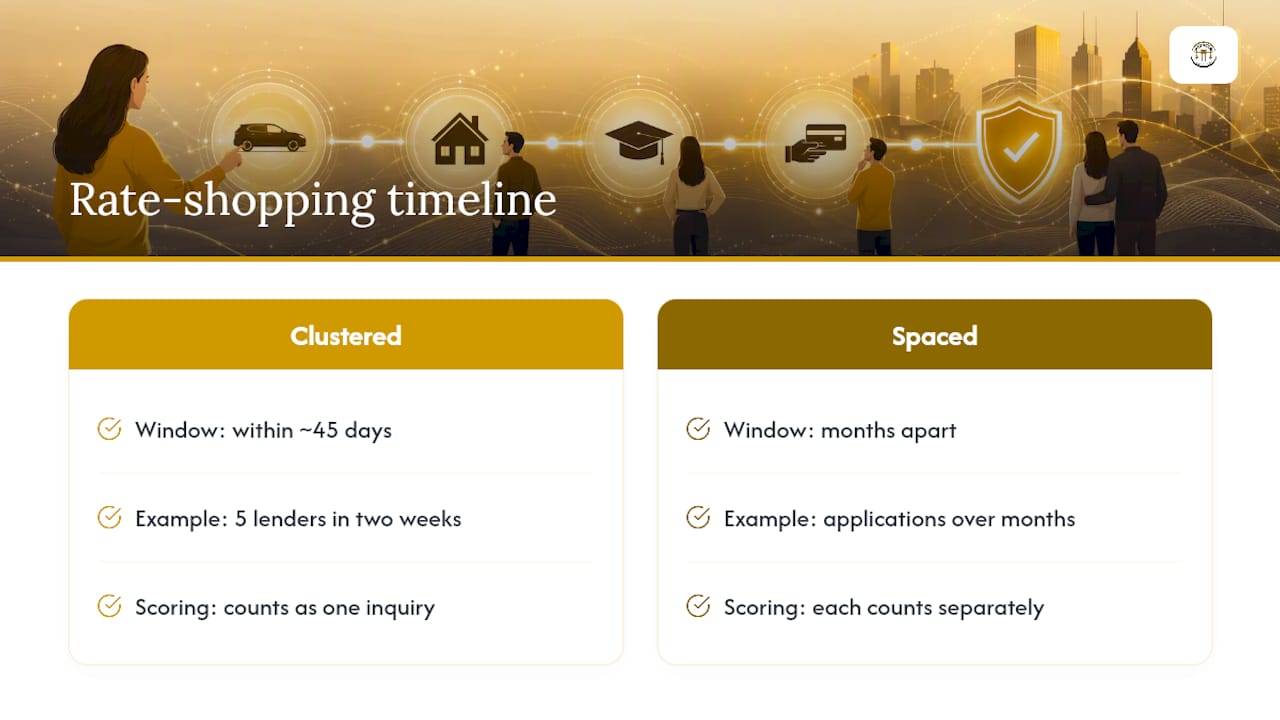
If you're planning to shop rates, cluster your applications into a short window instead of spreading them out over months. Spacing them too far apart is what turns a smart shopping strategy into multiple separate dings.
Which Hard Inquiries Can You Actually Remove?
Not every inquiry qualifies for removal, and it helps to know which category you're dealing with before you spend time on a dispute.
- Unauthorized or fraudulent inquiries. Someone used your identity to apply for credit you never requested. These are the strongest removal candidates.
- Inquiries without permissible purpose. A company pulled your credit without a legitimate business reason. Under the Fair Credit Reporting Act, that's a violation you can challenge.
- Duplicate entries. The same application sometimes gets reported twice, often when a loan gets shopped to multiple funding partners under one lender's name.
- Miscoded soft pulls. Occasionally a pre-qualification or account review gets logged as a hard inquiry by mistake.
- Inquiries older than 24 months. These should age off automatically, but they occasionally linger due to bureau errors.
What you can't remove is an accurate hard inquiry tied to an application you genuinely submitted, even if you regret applying. Be skeptical of any service promising to erase legitimate inquiries; that claim contradicts how the Fair Credit Reporting Act actually works.
Before filing anything, verify three things: the date matches a period when you were actually applying for credit, the company name is one you recognize or can trace back to a lender, and you can confirm whether you personally authorized that credit check.
How to Dispute a Hard Inquiry Step by Step
Here's the sequence that gets results without wasting weeks.
- Pull all three reports. Get your reports from AnnualCreditReport.com and list every hard inquiry by date, creditor name, and which bureau shows it. Equifax, Experian, and TransUnion don't always show the same inquiries, so check all three.
- Gather your evidence. Collect anything that proves you didn't apply: no application receipt, no confirmation email, and if identity theft is involved, your police report or FTC affidavit.
- Call the creditor first. Ask directly whether they pulled your credit and why. Request that they submit a correction to the bureau if the inquiry was made in error.
- File formal disputes with each bureau. Do this online through each bureau's dispute portal and follow up with certified mail. State plainly that the inquiry was unauthorized, list the date, and request removal under FCRA guidelines.
- Track the 30-day clock. Bureaus generally must investigate within 30 days. If they confirm the inquiry as accurate, you can request reinvestigation or escalate to the CFPB's complaint system.
Pro Tip: Send your written dispute to all three bureaus at once, even if the inquiry only shows on one report. Cross-bureau errors happen more often than you'd expect, and one letter covers your bases.
When Calling the Creditor First Works Faster Than a Bureau Dispute
Skipping straight to the bureau isn't always your fastest option. If the inquiry resulted from a clerical mix-up, going to the creditor directly can resolve things faster than the standard 30-day investigation.
- Find the exact company name listed on the inquiry, not just the brand you recognize.
- Call and ask them to confirm whether they pulled your file, and why.
- Request written confirmation once they agree to correct the record.
Pro Tip: Save every name, reference number, and date from that call. If the creditor doesn't follow through, that paper trail becomes your evidence for a formal bureau dispute.
This shortcut has limits. If the inquiry stems from stolen identity rather than a paperwork mistake, the creditor usually can't fix it alone. Fraud cases need the identity-theft process described next.
What to Do If the Inquiry Is Tied to Identity Theft
If someone used your information without permission, treat this differently than a routine dispute.
- File a report at IdentityTheft.gov, which generates an official recovery plan and a report you can submit to creditors and bureaus.
- Request an FCRA §605B block, which forces bureaus to block information resulting from identity theft rather than simply investigating it.
- Freeze your credit with all three bureaus and notify any lender tied to the fraudulent account.
- File a police report if the bureau or creditor requires one for the block to take effect.
- Escalate to the CFPB if a bureau ignores your identity-theft report or fails to honor the block.
An FCRA §605B block often moves faster than a standard dispute because it doesn't require the bureau to reinvestigate. It requires them to block the information outright once your identity-theft report is on file. If you're rebuilding after fraud more broadly, a complete recovery guide walks through the additional cleanup steps beyond just the inquiry.
What Happens After You File a Dispute?
Bureaus generally have 30 days to investigate. They'll either remove the inquiry, verify it as accurate, or occasionally reinvestigate if you submit new evidence. If it's removed, your score often recovers within the next reporting cycle, though the typical lift from a single inquiry removal is modest, often in the range of two to five points. If the dispute fails, you can request reinvestigation, add a consumer statement to your file, or file a CFPB complaint. For anyone juggling multiple bureaus or a tangled identity-theft case, that's usually the point where professional help starts to make sense.
When to Handle This Yourself vs. When to Get Help
If you've spotted one unauthorized inquiry with a clear paper trail, DIY disputes work fine; the process above will get you there. Once you're managing fraud across all three bureaus, juggling police reports, and chasing multiple creditors on a deadline, that's when bringing in help pays off. Some credit repair firms specialize in managing complex dispute work, including identity-theft cleanup, which can be very time-consuming. Either way, remember that inquiries are a minor score factor. Payment history and utilization move the needle far more.
— Danny
How Pioneercreditsolution Handles Inquiry Disputes and Credit Cleanup
Pioneercreditsolution gives you a direct path when disputes turn into a second job instead of a quick letter. Rather than leaving you to track three bureau portals, certified mail receipts, and creditor phone calls on your own, our team manages the dispute correspondence, documents your identity-theft claims, and follows up on reinvestigation deadlines so nothing slips through a 30-day window unanswered.

We're upfront about limits: an accurate, authorized inquiry isn't something anyone can legally erase, and you should be wary of any company that promises otherwise. Certain credit repair services offer faster handling of legitimate disputes, identity-theft blocking requests, and credit monitoring to catch unauthorized inquiries early. If you'd rather build your score up than fight bureau paperwork alone, our credit repair services start with a free consultation, and we'll tell you honestly whether your situation calls for a formal dispute or a different fix entirely.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Experian — information about hard inquiries
- MyFICO — how long hard inquiries stay on your credit report
- Consumer Financial Protection Bureau — how to dispute an error on my credit report
- Identitytheft
- Borrowell — how to dispute hard inquiries
FAQ
Is There a Way to Get Hard Inquiries Removed?
Yes, but only if the inquiry is unauthorized, duplicated, miscoded, or fraudulent. You dispute it with the bureau that shows it, or contact the creditor directly and ask them to submit a correction.
Can Hard Inquiries Cause a Low Credit Score Like 550?
Inquiries alone rarely drag a score down to that level; a low score usually reflects bigger factors like missed payments, high utilization, or collections. Removing an unauthorized inquiry might recover a small amount, typically two to five points, but rebuilding from a low score requires addressing payment history and balances too.
Do Hard Inquiries Ever Go Away on Their Own?
Yes. Hard inquiries fall off your report automatically after 24 months, and their effect on your score fades well before that, since scoring models mostly weigh the past 12 months.
How Many Points Will My Score Go Up if a Hard Inquiry Is Removed?
Most consumers see a small bump, often in the two to five point range, since a single inquiry carries limited weight in most scoring models. If you have several inquiries removed at once, the combined effect can be more noticeable, though results vary by credit profile.