
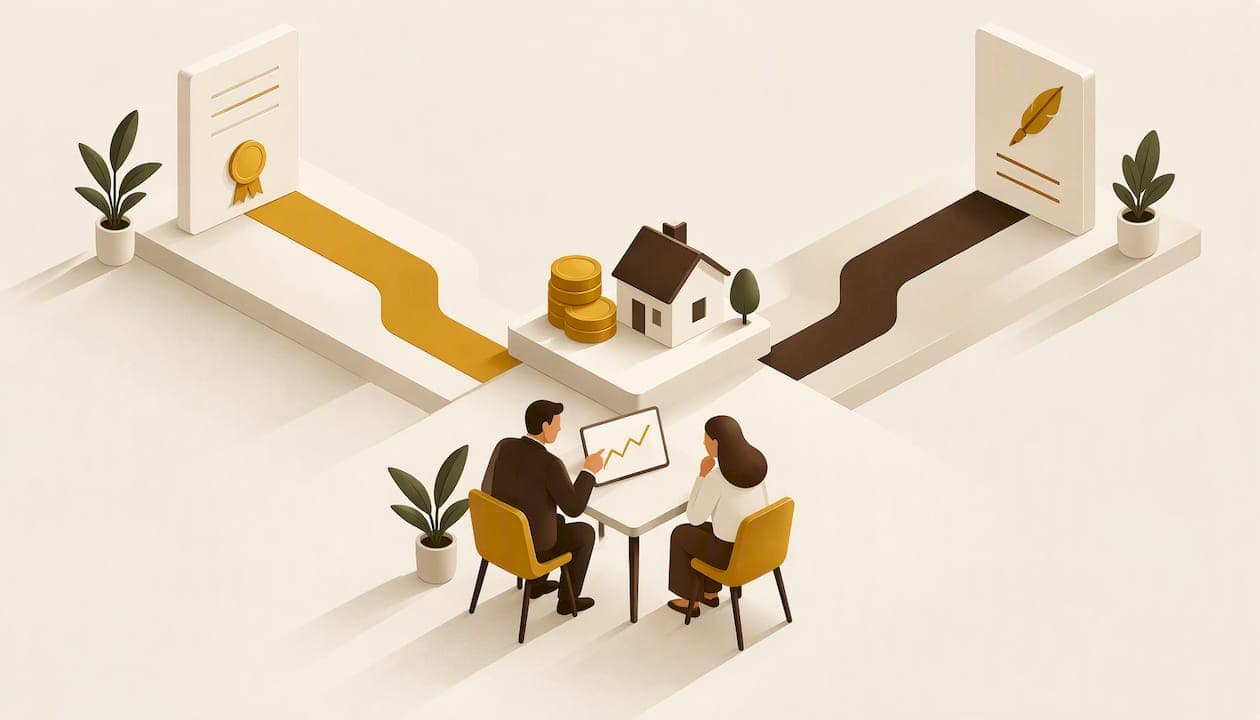
For the account or policy it covers, a valid beneficiary designation generally wins over your will. The reason is simple. A will controls what passes through probate. A beneficiary form is a contract with a financial institution, and the institution pays the person named on that form. So a will that leaves your life insurance to your daughter does not help her if the policy names your son. This guide shows what each document controls, where the two collide, and how to line them up so your wishes hold.
TL;DR
- A beneficiary designation controls the specific account or policy it is attached to. A will controls probate property and names your executor.
- When the two conflict, the designation generally wins for that asset.
- Name a primary and a contingent beneficiary, and review the forms after marriage, divorce, a birth or a death.
- Retirement plans can require your spouse's written consent to name someone else.
- You usually need both documents, coordinated, not one or the other.
Table of Contents
- What a will controls and what a beneficiary designation controls
- Side-by-side comparison
- Does a beneficiary designation override a will?
- Primary vs. contingent beneficiary
- Pay-on-death accounts vs. leaving the account in a will
- How the two documents work together
- How to complete or update a beneficiary form
- Perspective
- Where Pioneer Credit Solution fits
- Common mistakes to avoid
- FAQ
- Sources
What a will controls and what a beneficiary designation controls
A will is a writing that names the people who inherit your assets and names a representative to administer and distribute the estate, according to the American Bar Association. It reaches property that is in your name alone with no other transfer instruction attached. Think of a house titled only to you, a brokerage account with no named beneficiary, a car, jewelry and furniture.
A beneficiary designation works differently. It governs the specific contract or account where you filed it. The ABA lists joint-survivorship property, payable-on-death accounts, life insurance, retirement plans and employee death benefits as examples of assets that generally pass outside the will.
The Uniform Probate Code takes the same broad view. It defines a beneficiary designation to include insurance or annuity beneficiaries, POD accounts, TOD securities and retirement plans.
Assets that usually pass by designation
Montana State University Extension's 2025 guide lists the common candidates: life insurance and annuities, 401(k), 403(b) and 457 plans, IRAs, POD bank accounts and CDs, TOD securities accounts, and some transfer-on-death deeds. Availability of some of these, such as real estate transfer-on-death deeds, depends on your state.
Assets that usually pass by will
Property with no designation and no co-owner generally goes through probate under your will. That includes tangible personal property and anything you acquired later and never attached a beneficiary to.
Side-by-side comparison
| Feature | Will | Beneficiary designation |
|---|---|---|
| What it covers | Probate property in your name alone | The one account, policy or plan it is filed with |
| Where it lives | With you, your attorney or the court at death | With the bank, insurer or plan administrator |
| Goes through probate | Yes | Generally no |
| Names an executor | Yes | No |
| Can name a guardian for children | Yes | No |
| Who wins in a conflict | Loses for the covered asset | Generally wins for the covered asset |
| How you change it | New will or codicil, properly signed | New form filed with the institution |
Does a beneficiary designation override a will?
Generally, yes, for the asset it covers. The ABA's 2022 guide states that assets with a beneficiary designation pass under that designation rather than under a will or revocable trust. Montana State's example makes it concrete: a life insurance designation for a son defeats a later will provision leaving the same proceeds to a daughter.

This catches families by surprise because the will feels like the final word. It is the final word only for what the will actually controls. If you want to read more on how heirs and named beneficiaries differ, see our post on beneficiary vs. heir.
Exceptions and complications
A designation is strong, but it is not bulletproof. These are the situations that most often change the result:
- Spousal rights in retirement plans. The IRS explains that certain qualified plans must provide a qualified joint-and-survivor annuity and generally a pre-retirement survivor annuity to a married participant's spouse. Waiving or changing that generally takes written spousal consent. Some plans are exempt only if the death benefit is paid in full to the surviving spouse unless the spouse consents to someone else. Ask your plan administrator which rules apply to your plan.
- Outdated forms. The Financial Planning Association warns that an unchanged designation after divorce and remarriage can send life insurance proceeds to an unintended former spouse.
- No surviving beneficiary. Most contracts name a default beneficiary, often the owner's estate or certain family members, and default rules vary by institution and asset. When an asset falls to the estate, your will takes over.
- Divorce statutes and court orders. Some states automatically cancel an ex-spouse's designation, and some do not. A family law attorney in your state can tell you which applies.

Primary vs. contingent beneficiary
A primary beneficiary is first in line. A contingent beneficiary is the backup who receives the asset if the primary predeceases you or disclaims the asset, according to the ABA.
Why the backup matters: for real estate transfer-on-death deeds, the Uniform Law Commission states that a beneficiary who does not survive the owner generally loses the interest, though an anti-lapse rule may pass it to descendants. Do not count on that rule. Name a contingent beneficiary on every form that allows one.
You can generally name individuals, trusts and charities, and you can split an asset among several beneficiaries using percentages, per the same ABA guide. If you split, make the percentages add up to 100 and say what happens if one person is gone.

Pay-on-death accounts vs. leaving the account in a will
A pay-on-death (POD) designation is a beneficiary form on a bank account. Montana State separates POD for checking, savings and CDs from TOD registration for stocks, bonds and mutual funds. The ABA glossary notes that POD and TOD are common terms for a designation that moves an account to a named person without probate.
During your life, you keep ownership and control. ARAG's guide describes the POD account as keeping the owner in control while naming who receives the funds at death. If your will says "my savings go to my niece" but the account is POD to your brother, the bank pays your brother.
How the two documents work together
You do not choose one. The ABA recommends having both and coordinating their terms. Designations move the covered assets. The will provides the framework for probate assets and backup instructions for anything that fails to pass by designation.
The ABA also says to sign a will even when designations are your main transfer method. A will covers assets with no designation, assets you acquired later and forgot to designate, tangible personal property, and refunds payable to you after death. It also names your executor. If you are sorting out that role, our guide to executor vs. trustee duties explains the first 90 days.
A will only works if it is signed correctly. Our six-step notarization checklist walks through the signing, and a trust may fit better if you want to avoid probate on more of your estate: see probate vs. trust.
How to complete or update a beneficiary form
- List every account and policy. Include old 401(k)s, IRAs, life insurance, annuities, bank and brokerage accounts.
- Request the current designation from each institution. Do not assume the form matches what you remember.
- Choose primary and contingent beneficiaries. Use full legal names, relationships and percentages.
- Think about minors. The ABA notes that life insurance payable directly to a minor may require a court-appointed guardian or conservator, and that naming a trust or custodial account can avoid that result.
- Check spousal consent rules if the account is an employer retirement plan.
- File the form with the institution and keep the confirmation.
- Match your will and trust to the forms so they do not contradict each other.
After a spouse dies, the IRS advises contacting the employer or plan administrator, completing the change-of-beneficiary forms and submitting them signed. Review forms after any marriage, divorce, birth or death.
Perspective
We see the same pattern with clients rebuilding their finances. They work hard to repair credit, buy a home, open a business, and then leave the paperwork that protects it all untouched. A beneficiary form signed years ago can quietly override the will you finally got around to writing.
Our view is that financial health is a full cycle: recover, build, protect. Estate planning, including wills, living trusts, special needs trusts and mobile notary signing, belongs in that cycle. If you have a child with special needs, for example, how the assets are titled and designated matters a great deal, and it should be planned deliberately with an attorney's guidance.
Start by listing every account that has a beneficiary line. It takes an afternoon, and it can spare your family months of confusion.
Yvette V.
Where Pioneer Credit Solution fits
As your credit improves, your balance sheet changes: a new mortgage, a business loan, a life insurance policy, a retirement account. Each one is a new place where a beneficiary decision gets made. We help individuals and entrepreneurs repair credit, build business credit and prepare for home, auto and business financing, and we also offer estate planning services and mobile notary signing.
If you are ready to move from recovery to growth, see our full range of services or explore financing options for personal and business needs. Get your free consultation and we will point you to the right next step.
If a lower score is what holds you back, our credit repair services are designed to address negative items on your report so you can qualify for better terms.
Common mistakes to avoid
- Naming your estate by accident. Leaving the beneficiary line blank or naming the estate pushes the asset into probate, where your will governs it.
- Naming a minor directly. Use a trust or custodial arrangement, as described above.
- Forgetting an ex. Update every form after a divorce instead of assuming a law will do it.
- Contradicting yourself. A will that splits everything equally does not equalize a policy that names only one child. Adjust the will or the form so the total result is what you intend.
- Moving an IRA into a trust without a plan. Funding rules for retirement accounts are specific. Our post on funding a trust explains why owners usually keep IRAs in their own names.
FAQ
Does a beneficiary override a will?
For the specific account or policy, generally yes. The institution pays the person on its form, not the person in your will. The exceptions include spousal consent rules for some retirement plans and state divorce laws.
What is the difference between a will and a beneficiary?
A will is a document that directs probate property and names your executor. A beneficiary is the person you name on an account or policy to receive it at death. They are two separate transfer tools that should say the same thing.
Is pay on death better than a will?
They do different jobs. A POD designation moves one bank account directly to a named person, and you keep control during your life. A will covers everything else. Most people use both.
Who should you name as a beneficiary?
You can generally name individuals, trusts or charities, and you can split shares by percentage. Name a contingent beneficiary too. If a child is the beneficiary, ask an estate planning attorney about naming a trust instead of the child directly.
What happens if no beneficiary is named?
Most contracts name a default, often your estate or certain family members, and the rules differ by institution. If the asset lands in your estate, your will controls where it goes.
Sources
- Introduction to Wills, American Bar Association
- Glossary of Estate Planning Terms, American Bar Association
- Beneficiary Designations in Estate Plans, American Bar Association
- Uniform Probate Code, Uniform Law Commission
- Uniform Real Property Transfer on Death Act, Uniform Law Commission
- Designating Beneficiaries to Avoid Probate, Montana State University Extension
- Qualified Joint and Survivor Annuity, IRS
- Notice 2014-19, IRS
- Death of Spouse, IRS
- Are You and Your Beneficiary Designations Up to Date?, Financial Planning Association
- Ensure Your Legacy with Non-Probate Asset Transfers, ARAG