
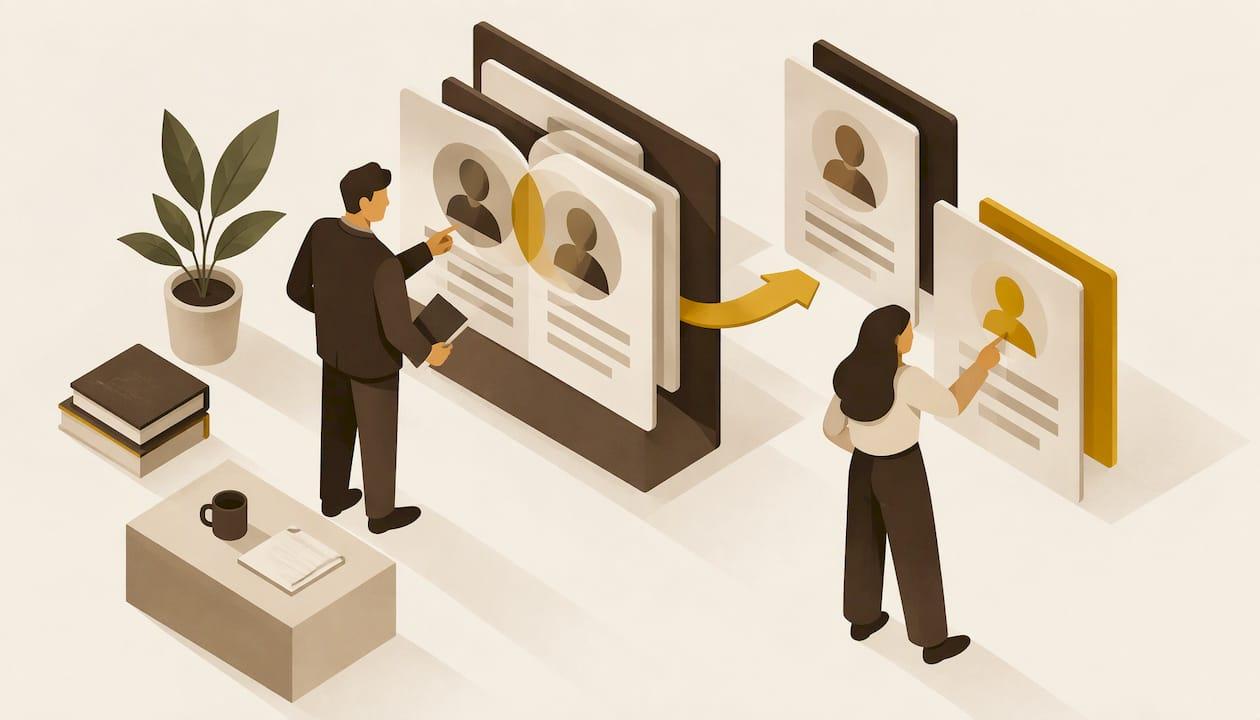
A mixed credit file means a credit bureau has blended another person's information into your report, usually because your names, addresses, birth dates or Social Security numbers look alike. You fix it by pulling all three reports, marking every item that is not yours, and sending written disputes with proof to both the bureau and the company that supplied the data. The bureau then has a legal clock to investigate. Below, we walk through the signs, the causes, the dispute steps and what to do if the error does not go away.
TL;DR
- A mixed file happens when a bureau matches your identity to someone else's, most often a relative with the same or a nearly identical name.
- Check all three reports for accounts, addresses, employers or name variations that are not yours.
- Dispute in writing with the bureau and with the furnisher, include supporting documents, and keep proof of delivery.
- Bureaus generally have 30 days to reinvestigate and must correct or delete what cannot be verified.
- If the same wrong data keeps returning, escalation options exist, and our team can help you build and manage the dispute file.
Table of Contents
- What a mixed credit file is
- Why bureaus merge two people's information
- Signs your report may be mixed
- How to check all three reports
- How to dispute a mixed credit file
- Timeline at a glance
- What to do if the mix-up comes back
- A note on the 609 letter and other shortcuts
- Perspective: why a mixed file deserves a professional-grade dispute
- Get your file corrected with Pioneer Credit Solution
- Preventing a mixed file
- FAQ
- Sources
What a mixed credit file is
A mixed file is a credit report that contains information about two or more people. The Consumer Financial Protection Bureau (CFPB) uses the term for this exact error and lists accounts belonging to another person with the same or a similar name among the common mistakes to look for on your report.
The result can go in either direction. Someone else's late payments, collections or high balances can drag your score down. Or your clean history can be tangled up with a stranger's, which becomes a problem the day that person's debts start showing up under your name.
A mixed file is different from identity theft. In a mix-up, nobody necessarily acted in bad faith: the bureau's matching system simply linked two people who look alike on paper. In identity theft, someone deliberately used your details to open accounts. The fixes overlap, but if you suspect fraud, see our guide to identity theft recovery and fraud alerts.

Why bureaus merge two people's information
Credit bureaus receive data from thousands of lenders, collectors and other furnishers. Each record has to be matched to a person. When the matching rules are loose, two people become one file.
Experian explains that mixed files are caused by two people sharing nearly identical identifying information, such as names, addresses and dates of birth, and even Social Security numbers that differ by only one or two digits. It notes the problem shows up most often with a father and son who share the same name.
Common patterns
- Generational names: a "Robert Johnson, Sr." and "Robert Johnson, Jr." at the same address. The Georgia Attorney General's office specifically tells consumers to look for this kind of mixed information.
- Similar Social Security numbers: a typo by a lender or a one-digit difference can link two files.
- Shared addresses: family members, roommates or past tenants at the same address.
- Very common surnames: the 2010 census found more than 2.4 million people named Smith and 1.9 million named Johnson, as the Federal Register notice on name-only matching points out.
That same 2021 advisory opinion states that matching based solely on identical or similar first and last names is not a reasonable procedure to assure maximum possible accuracy under the Fair Credit Reporting Act (FCRA). In plain terms, a bureau cannot lawfully rely on a name alone.
Signs your report may be mixed
Most people discover a mixed file when a loan is denied, a rate comes back higher than expected, or a collection call arrives for a debt that is not theirs. Better to find it earlier. Look for these red flags:
- Accounts you never opened, especially from lenders you have never used.
- Addresses where you never lived.
- Name variations or aliases that are not yours, including a different suffix such as Jr. or Sr.
- Employers you never worked for.
- A Social Security number or birth date that is off from yours.
- Collections, late payments or public records that do not match your history.
- A score that is far lower, or far higher, than your own history would suggest.
The CFPB's advice when reviewing a report is to confirm it contains only items about you, including identity details and accounts belonging to someone with the same or a similar name.
Why it matters beyond your score
A mixed file can affect mortgage approvals, auto loan rates, apartment applications and business funding. If you are preparing to buy a home or apply for a business loan, a clean and accurate file is the foundation, and it is worth checking before any lender pulls your credit.
How to check all three reports
The three nationwide bureaus are Equifax, Experian and TransUnion. A mix-up can exist at one bureau and not the others, because each runs its own matching system. Review all three.
When you read each report, work through it in this order:
- Personal information: names, addresses, birth date, Social Security number, employers.
- Accounts: every open and closed tradeline. Mark any you do not recognize.
- Collections and public records: check names and account numbers.
- Inquiries: look for applications you did not make. Our guide to hard inquiries you can remove explains which types may qualify.
Print or save each report. Circle every disputed item and write a short note on why it is not yours. This becomes the core of your dispute package.
How to dispute a mixed credit file
The CFPB says to start by disputing the error with the credit reporting company, explaining in writing what is wrong and why, and including copies of supporting documents. You should also contact the company that provided the information, called the furnisher.
Step 1: Gather proof of who you are
Useful documents include a copy of your driver's license, a Social Security card or statement, a recent utility bill showing your address, and anything showing the other person's different details, such as a different middle name, birth date or suffix.
Step 2: Write the bureau letter
The CFPB recommends that a mailed dispute include:
- Your contact information and the report confirmation number
- Each error you want fixed, with account numbers
- A clear explanation of why you are disputing it
- A request that the information be removed or corrected
- A copy of the report with the disputed items circled
- Copies of supporting documents
It also recommends certified mail with a return receipt, so you can prove when the bureau received your dispute.
Be specific about the mix-up. Say plainly that the listed accounts belong to another person and not to you, and name the identifiers that differ. Vague letters invite vague answers.
Step 3: Write to the furnisher
To dispute information a furnisher provided, send a written dispute to the address on your report or the address the furnisher specifies for credit reporting disputes. This matters in a mixed file because the bureau may "fix" the item and then receive the same wrong data again from the lender. Disputing at the source helps keep it from returning.
Step 4: Track the deadlines
Under 15 U.S.C. § 1681i, when you dispute the accuracy or completeness of information, the bureau must conduct a reasonable reinvestigation free of charge and record the item's current status or delete it before the end of the 30-day period after receiving your notice. Within 5 business days, it must notify the furnisher of the dispute and pass along the relevant information you sent.
The CFPB adds that furnishers generally must investigate and respond within 30 days, and if the information is wrong or cannot be verified, they must update or remove it and notify all the credit reporting companies. A bureau is not required to investigate a dispute it reasonably determines is frivolous or irrelevant, but it must send a notice explaining that decision within five business days. That is one more reason to send a detailed, documented letter.
Disputes are free. The Georgia Attorney General's office confirms you can dispute errors at no cost by notifying in writing both the credit reporting company and the person or company that provided the information.
Timeline at a glance
| Stage | What happens | Timing |
|---|---|---|
| You mail the dispute | Bureau and furnisher each get a written dispute with documents | Day 0 |
| Bureau notifies the furnisher | Passes along your dispute and documents | Within 5 business days |
| Bureau reinvestigation | Corrects or deletes unverifiable items | Generally within 30 days |
| Furnisher response | Updates or removes wrong data, notifies all bureaus | Generally within 30 days |
| Results letter | You receive the outcome and an updated report | After the investigation |

What to do if the mix-up comes back
Some mixed files are stubborn. The same account may reappear, or a bureau may respond that the information was "verified." Here is how to keep moving.
- Re-dispute with new evidence. Add anything that distinguishes you from the other person: a birth certificate, a court-issued name document, a Social Security card, older addresses.
- Dispute with the furnisher again. If a lender keeps reporting the other person's account to your file, the source needs correcting.
- Pull fresh reports from all three bureaus after each round, to confirm that a fix at one bureau did not stay isolated.
- Keep a log. Dates, confirmation numbers, names and copies of every letter.
Your legal protections
The FCRA requires bureaus to follow reasonable procedures to assure maximum possible accuracy. The Supreme Court's 2016 opinion in Spokeo v. Robins notes that a person who willfully fails to comply can be liable for actual damages or statutory damages of $100 to $1,000 per violation, plus costs, attorney's fees and possibly punitive damages.
Failing to comply through negligence can also create liability. The Fourth Circuit explained in Ausherman v. Bank of America that the FCRA imposes civil liability on any person who willfully or negligently fails to comply with its requirements. And according to the Sixth Circuit, the FCRA creates a private right of action against a furnisher that fails its duties after a dispute.
If a mixed file has cost you a loan, a job opportunity or a home, talk to a consumer protection attorney about your specific situation. Whether a violation was negligent or willful, and what damages apply, depends on the facts and your state. For your credit file itself, our team handles the dispute side.
A note on the 609 letter and other shortcuts
Search results are full of template letters that promise to wipe items off a report. For a mixed file, the winning approach is not a template. It is accurate identification of what is not yours, backed by documents and sent to the right parties. If you want to understand what that popular template can and cannot do, read our explainer on the 609 letter.
Perspective: why a mixed file deserves a professional-grade dispute
We see mixed files regularly, and they are some of the most frustrating errors a client can face. The person did nothing wrong, yet a lender is looking at someone else's history.
Our approach is to treat the file as a project. We start with a credit profile analysis across all three bureaus, map every item that does not belong, and organize the proof so each dispute is specific and documented. Then we follow the responses and press for corrections that stay corrected.
Clean data is also the starting point for what comes next. Once your file is accurate, we can help you boost your score, prepare for a mortgage or auto loan, and build business credit. We designed our services to move clients from recovery to growth, and fixing a mixed file is often step one.
Yvette V.
Get your file corrected with Pioneer Credit Solution
If your report contains information that is not yours, our team can help you identify it, organize your documents and manage the dispute process from start to finish. We combine credit profile analysis and credit monitoring with personalized strategies, so you know what is on your file and what changes.
Ready to move forward? Get your free consultation on our credit repair services. Once your report is accurate, we can also help you explore personal and business financing options and ways to boost your score for a home, a car or a business.
Preventing a mixed file
You cannot control how a bureau matches records, but you can lower your risk and catch problems early.
- Use your full legal name consistently, including any suffix such as Jr. or Sr., on every application.
- Double-check your Social Security number on forms. A one-digit typo can link you to another person.
- Keep your address history clean. Update lenders when you move.
- Review your reports regularly so errors are caught before a major application.
- Use credit monitoring to be alerted to new accounts and changes.
- If a relative shares your name, talk to them about using full identifiers on applications as well.
If you are planning a big purchase, check your reports well ahead of time. A dispute can take weeks, and you do not want to find a mix-up in the middle of a mortgage application. Related reading: what do credit repair companies actually do and what to expect on credit repair costs and timelines.
FAQ
What is a mixed credit file?
It is a credit report that includes information belonging to another person, usually someone with a similar name, address, birth date or Social Security number. The CFPB treats it as a common credit report error. It can lower your score or hide someone else's problems behind your name.
How long does it take to fix a mixed credit file?
By law, a bureau generally must complete its reinvestigation and correct or delete unverifiable information within 30 days of receiving your dispute. Furnishers generally have 30 days to respond as well. Complicated mix-ups may need a second round with additional documents.
Does disputing a mixed file cost money?
No. Disputing an error directly with a bureau and a furnisher is free under the FCRA. If you want help organizing documents, tracking responses and following up, our team can manage the process for you under a signed agreement.
Is a mixed file the same as identity theft?
No. A mixed file usually comes from a matching error between two people who look alike on paper. Identity theft involves someone deliberately using your information. If you see accounts you did not open and suspect fraud, consider a fraud alert and follow identity theft recovery steps.
Can a mixed file stop me from getting a mortgage?
It can. Lenders rely on your reports and scores, and another person's late payments or collections can lower both. Correcting the file before you apply gives you the most accurate picture to work from.
Sources
- CFPB: What are common credit report errors that I should look for?
- CFPB: How do I dispute an error on my credit report?
- Federal Register: Fair Credit Reporting; Name-Only Matching Procedures
- Experian: How Can I Separate the Credit Reports of a Father and Son?
- Georgia Attorney General Consumer Ed: Credit Report Errors
- 15 U.S.C. § 1681i: Procedure in case of disputed accuracy
- Spokeo, Inc. v. Robins (2016)
- Ausherman v. Bank of America Corp. (4th Cir. 2003)
- Sixth Circuit on FCRA private right of action against furnishers